Beginner Stock Market Investing: What the Government’s £20m Push Means for You
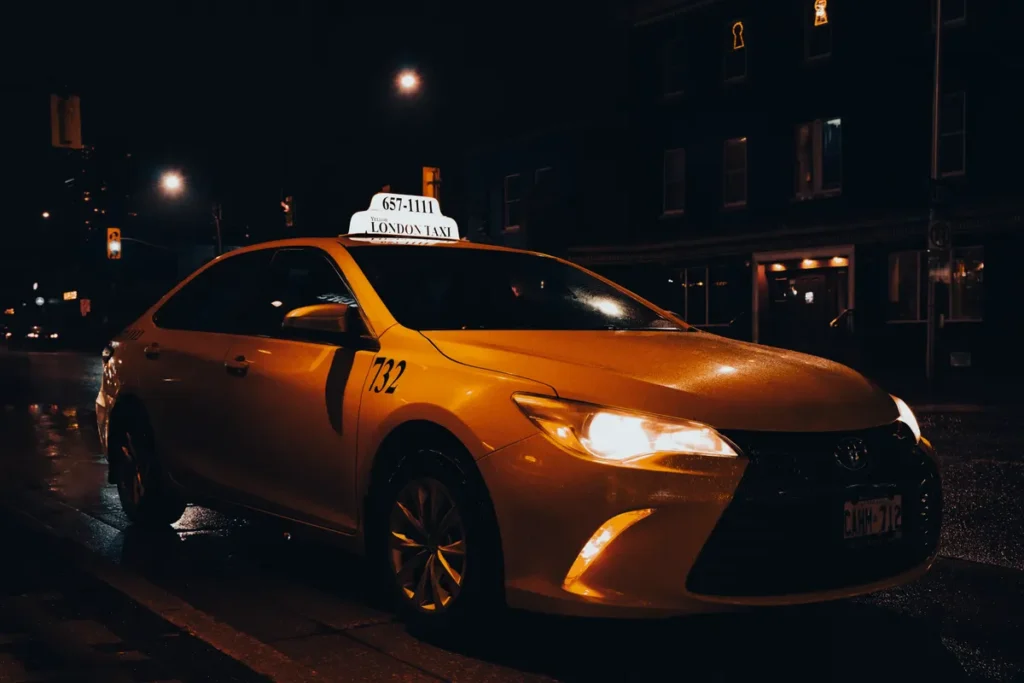
Beginner stock market investing has never had a higher-profile champion: the UK government this year launched a national campaign to encourage ordinary savers to move their money out of low-interest cash accounts and into investments, and it is spending a reported £20 million over three years to do it, according to CNBC. The initiative, called ‘savvy squirrel’, spans television, social media and even a fleet of branded taxis rolling out across cities including Leeds, Bristol, Cardiff, Norwich and Glasgow, according to the Investment Association.
The campaign exists because a surprisingly large pool of money is sitting idle. The Financial Conduct Authority (FCA), which regulates financial services in the UK, found that around 7 million adults hold more than £10,000 in cash savings that could, in the FCA’s view, be put to better use in the market. The core argument is straightforward: money left in an account that pays interest below the rate of inflation loses purchasing power over time, even if the balance never falls.
What Beginner Stock Market Investing Actually Involves
Stocks and shares, also called equities, represent a small ownership stake in a company. When that company does well, the value of your stake tends to rise; when it struggles, it can fall. Buying into a single company therefore carries real risk, which is why most guidance for newcomers points towards funds instead. A fund pools your money with that of other investors and spreads it across many companies, sectors, countries and asset types, including bonds.
‘If you were to start with a multi-asset fund, you would have diversification from day one,’ says Sarah Coles, head of personal finance at AJ Bell. For those who find even fund selection daunting, readymade portfolios go one step further, with a professional choosing and managing the mix on your behalf. ‘A ready-made portfolio is an excellent way to grow your money while keeping things simple,’ says Ben Faulkner of EQ Investors. ‘All the hard work of researching and stock-picking to curate a diversified portfolio is done for you by a professional.’ Low-cost index funds, which simply track a broad market rather than attempting to beat it, are another option Faulkner flags for cost-conscious investors.
You can open an investment account with as little as £1 on platforms including Hargreaves Lansdown, Vanguard, AJ Bell, eToro, Wealthify, Monzo, Plum, Moneybox and others. Fees vary: some platforms charge a percentage of your portfolio’s value, others a flat fee. The type of investments available also differs between providers, so it is worth checking before you open an account.
The Accounts Worth Knowing About
Most platforms offer a general investment account, but the most tax-efficient option for many people is a stocks and shares ISA (Individual Savings Account). Any returns you earn inside an ISA are free from UK tax. The annual allowance is £20,000 for an adult ISA and £9,000 for a Junior stocks and shares ISA opened for a child.
One practical question is when to invest. The common answer among practitioners is that time in the market tends to matter more than trying to pick the right moment to enter. Setting up a regular monthly payment, rather than investing a lump sum all at once, means you buy at a range of prices: sometimes higher, sometimes lower, which smooths out the effect of market swings over time.
Emilie Bellet, founder of Vestpod, a community that runs courses, events and a podcast to help people improve their financial lives, points to two stubborn barriers that hold people back: the belief that you need to know everything before you start, and the myth that you need a large sum of money to begin. Financial advisers generally recommend that any money you put into the market should be money you can leave untouched for at least three to five years, giving it time to recover from any short-term falls. That means having a separate cash buffer for emergencies first.
Three fund managers, asked what they do with their own money, converge on the same themes. Alexandra Jackson, director of equities at Rathbones Asset Management, says she focused on ‘building good habits’ rather than chasing winning stocks: investing regularly, diversifying holdings and using tax wrappers such as pensions and ISAs. Sabrina Denis, investment specialist at Janus Henderson Investors, stresses that genuine diversification means ‘holding things that behave differently from one another’, not five technology funds that all own the same ten stocks. Daniel Bland, head of sustainable investment management at EQ Investors, warns that most people only start worrying about markets after a run of bad news, by which point prices have already fallen. ‘Investors who stick to a long-term plan tend to be rewarded for it,’ he says.
Bellet’s closing caution is perhaps the most useful anchor for anyone tempted by finfluencer tips: ‘Don’t be drawn into investing in something because everyone seems to be talking about it, or because you feel rushed into making a decision. Be wary of anything that promises easy returns.’ The FCA’s finding that 7 million adults are sitting on more than £10,000 in cash suggests the appetite is there. The savvy squirrel campaign, now rolling out from Glasgow to Cardiff, is the government’s attempt to convert that appetite into action.
When investing, your capital is at risk and you may get back less than you invested. Past performance does not guarantee future results.